
Business Tax Consultant: How Professional Guidance May Help Navigate Complex Tax Rules

Recordkeeping, reporting, and compliance support provided by tax consultants
Recordkeeping guidance from consultants often centers on documenting the facts and business purpose that support tax treatments. Advisors may describe which documents—contracts, receipts, time records, or invoices—typically substantiate particular deductions or classifications. They can also suggest formats for organizing records to streamline preparation of tax returns and facilitate responses to inquiries. Such recommendations are informational and intended to improve traceability between business activities and tax reporting lines, rather than to provide definitive legal protection in every circumstance.
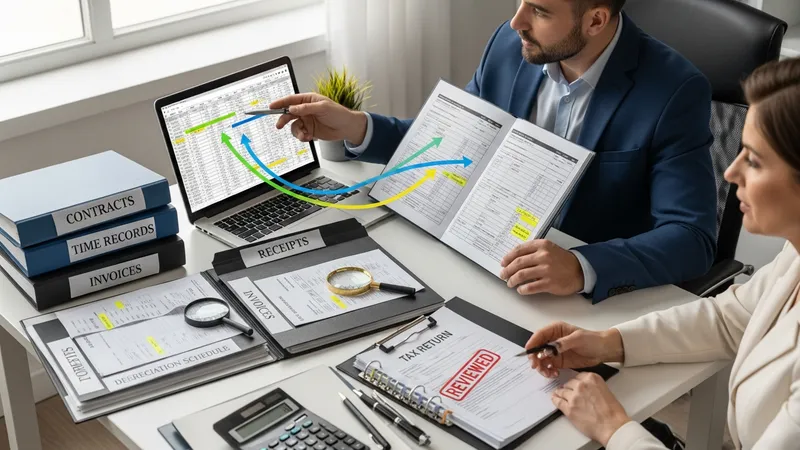
For reporting, consultants typically explain how accounting classifications map to tax forms and schedules. This mapping can identify timing differences between book and tax income, depreciation bases, or tax-specific adjustments. Firms may prepare or review draft returns to ensure consistency with source records and to flag areas that may warrant additional documentation. These activities are framed as quality-control and interpretation services, which may reduce the likelihood of inadvertent reporting errors when implemented by internal teams.
Consultants may also outline common filing obligations and deadlines relevant to typical business operations, including periodic estimated payments and informational returns. They often emphasize the need for timely record retention and may advise on retention periods commonly cited in administrative guidance. This guidance generally reflects prevailing administrative practices and is presented to help organizations align internal calendars and workflows with external filing timelines, not as a schedule of mandatory actions imposed by the advisor.
Where electronic filing and digital recordkeeping are used, consultants can describe workflow adjustments that often streamline compliance. Examples include reconciling payroll systems to wage reporting, tagging transactions for tax categories, or maintaining audit trails for adjustments. Such process descriptions typically include pros and cons of different approaches and considerations for internal control, allowing management to evaluate which methods align with their accounting systems and operational constraints.