
Business Tax Consultant: How Professional Guidance May Help Navigate Complex Tax Rules

Roles and services offered by tax consultants and related professionals
Certified Public Accountant (CPA) tax advisory services often focus on reconciling financial records with tax reporting requirements and preparing or reviewing tax filings. A CPA may generate schedules that support income recognition, deductions, and tax provision entries used in financial statements. Tax attorneys provide legal interpretation and may assess the legal defensibility of tax positions or represent a client in administrative proceedings. Outsourced advisory firms can offer periodic compliance checks, research memos, and implementation support for particular transactions. Each provider type typically brings a different emphasis—accounting alignment, legal analysis, or operational implementation—so organizations may engage more than one type depending on complexity and risk.
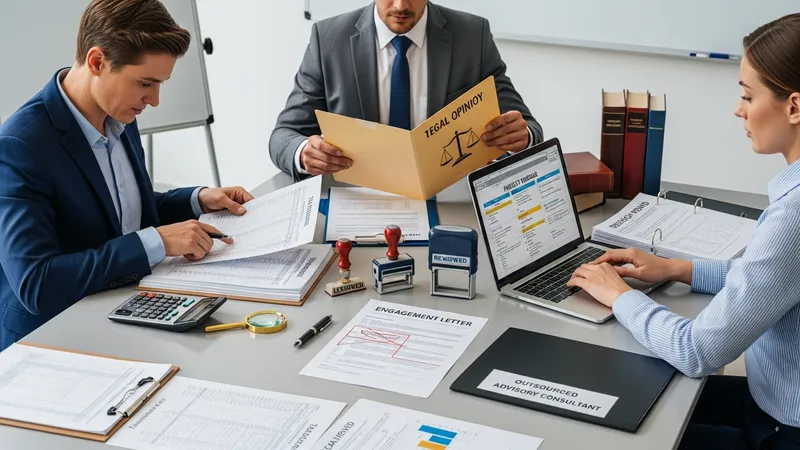
When selecting the mix of services, organizations often consider factors such as transaction complexity, internal capacity, and existing documentation practices. For routine filings, a CPA-led approach that integrates with bookkeeping systems may suffice. For transactions with material legal questions—such as allocation of liabilities in restructurings—tax attorneys may be consulted to interpret statutes and case law. Outsourced advisors may be engaged for targeted projects where internal resources are limited. These arrangements are typically described in engagement letters that outline scope, deliverables, and fee arrangements in neutral terms.
Typical deliverables vary by service type and engagement length. CPAs may produce return drafts, reconciliation schedules, and checklists for recordkeeping; tax attorneys often provide legal memoranda and position analyses; outsourced advisors may deliver research notes and implementation checklists. The level of detail and format of documentation can influence internal processes, for example by clarifying what invoices or contracts should document a transaction. Organizations often treat these outputs as informational inputs that inform internal decision-making and controls rather than as directives.
Costs and timelines of engagements commonly depend on the volume of transactions, the degree of uncertainty, and the level of documentation review required. Short-term research memos may be completed in days to weeks, while comprehensive compliance reviews or transaction analyses may span months. Fee structures vary and may include hourly billing, fixed-fee projects, or retainer arrangements; firms typically describe these options without guaranteeing outcomes. Organizations often weigh these practical trade-offs when determining the appropriate level of external support.