
Private Lending Companies: How They Operate And Structure Loans

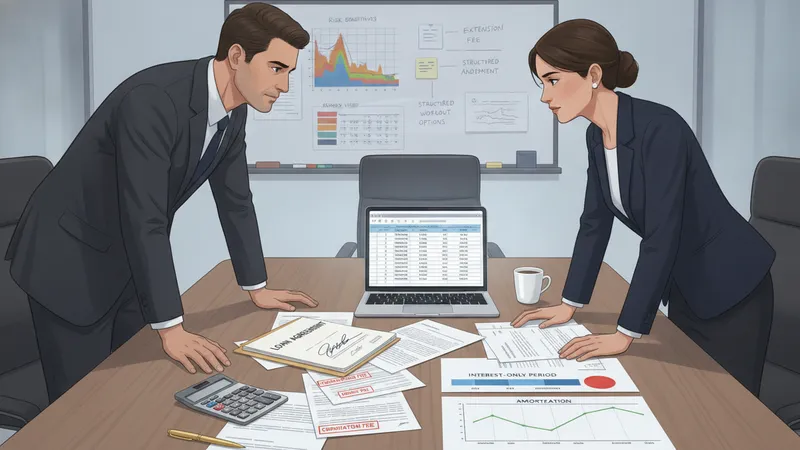
Interest rates, fees, and repayment terms commonly observed
Pricing in private lending generally reflects asset risk, term length, and liquidity considerations. Interest rates may be stated as fixed spreads, variable rates tied to reference indices, or blended yields that incorporate fees and arrangement charges. Origination fees, commitment fees, and servicing fees are additional cost elements that can materially affect the effective interest burden. Parties often negotiate fee timing and capitalization to match the borrower’s cash flow and project lifecycle.
Repayment profiles often align with expected exit strategies. Short-term investments may rely on project completion, resale, or refinance as the repayment source, leading to interest-only periods followed by a balloon payment. Longer-term business financings may use amortizing schedules to reduce principal risk over time. Lenders and borrowers frequently model sensitivity to slower-than-expected exits to evaluate potential extension fees, maturity amendments, or structured workout options before default occurs.
Prepayment and penalty provisions influence refinancing flexibility. Some agreements permit prepayment without penalty after defined intervals, while others include prepayment premiums or breakage charges tied to lost yield. Late payment remedies and default interest rates are commonly specified to preserve recovery incentives and to compensate for increased enforcement costs. Transparency in how these terms are calculated is important for both parties to anticipate financial outcomes during stress scenarios.
Fee disclosure and documentation practices vary; however, clear schedules that itemize all recurring and one‑time charges are standard in prudent transactions. Lenders may present illustrative amortization and fee schedules during due diligence so borrowers can project total financing costs. Careful review of these schedules and assumptions can help participants assess affordability and align expectations around refinancing, sale, or operational cash flow needed to meet repayment obligations.