
Pension Options For Seniors: Understanding Key Retirement Income Choices

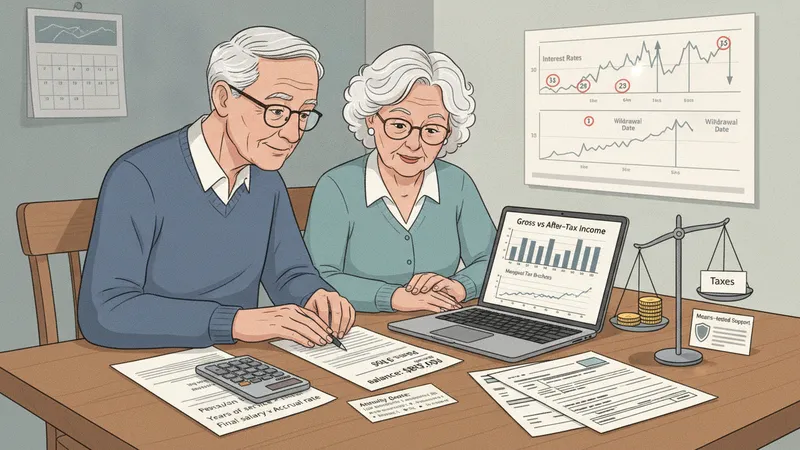
Tax treatment and benefit calculation methods affecting retirement income
Tax rules often shape net retirement income more than gross payouts, since different sources may be taxed in distinct ways. Some contributions are pre-tax and withdrawals are taxable, while others are made with after-tax funds and offer tax-free distributions later. The timing of withdrawals can affect marginal tax rates in a given year and influence social benefits or means-tested support in some systems. Understanding the typical tax profile of each income source helps clarify net cash flow after statutory deductions.
Benefit calculations for defined benefit plans usually use explicit formulas involving service years and salary measures; for account-based plans, the accumulated balance and assumed conversion factors determine periodic payout amounts. Annuity pricing reflects life expectancy assumptions, prevailing interest rates, and product costs, which means income from conversion of a balance may rise or fall with market conditions. Comparing estimates on an after-tax, after-cost basis provides a clearer view of practical income potential.
Commonly used analytical techniques include projecting several withdrawal sequences, modeling tax effects under different income scenarios, and running sensitivity checks for interest-rate and longevity changes. These methods may reveal that small adjustments to claiming age or withdrawal sequencing can materially alter net outcomes. While modeling cannot ensure a specific future, it can help identify scenarios that may warrant further attention or conservative planning buffers.
An informational tip is to collect documentation showing how each plan treats taxes, indexation, and survivor provisions, and to use these inputs consistently in any comparison model. Where professional projections are sought, verify assumptions about longevity and discount rates, and treat differing assumptions as part of a range rather than a single forecast.